
Many Irish businesses build up cash reserves beyond what they need for day-to-day running, whether from a strong trading year, the sale of an asset or simply careful management over time. Left sitting in a business current or deposit account, that surplus often earns very little, and can lose real value once inflation is taken into account.
A corporate investment account offers an alternative: a way to put that surplus to work, generating returns to support the business’s short-, medium- and long-term goals, without needing to draw the funds out personally. Here, Fairstone looks at what corporate investment involves, the benefits it can offer and what to think about before getting started.
Corporate investment is the process of using a company’s own surplus funds, rather than funds belonging to its directors or shareholders personally, to invest in financial assets such as shares, bonds, managed funds or life assurance-based investment policies.
It is carried out through a corporate investment account, held in the company’s name, which keeps the investment entirely separate from personal finances and subject to corporation tax rules rather than personal tax rules.
This approach suits businesses that have built up cash reserves comfortably beyond their working capital needs and want that money to do more than sit idle. Rather than leaving surplus profits in a low-interest business account, or extracting them personally and facing income tax, USC and PRSI along the way, the company can invest directly, keeping options open for future expansion, acquisitions, key employee benefits or eventual extraction on more favourable terms.
Yes. A company can use surplus funds to buy shares directly in another business, whether as a minority stake, a strategic partnership or a longer-term financial holding. This decision sits with the company’s directors, who have a duty to act in the best interests of the company, so any significant direct investment, particularly in a connected or related business, should be properly assessed, documented and approved at board level.
The tax treatment also differs from other forms of corporate investment. Gains on direct shareholdings are generally taxed as chargeable gains at 33%, the same rate that applies to capital gains tax, rather than the 25% rate that applies to investment income such as deposit interest. Dividends received from other Irish resident companies are usually exempt from further corporation tax.
Direct investment can be rewarding, especially where the target company is in a growth phase or operates in a complementary sector, but it also carries real risks, including illiquidity and the difficulty of exiting an unlisted holding. Thorough due diligence, and professional advice, are essential before committing company funds this way.
Used well, a corporate investment account offers several advantages over leaving surplus cash on deposit, including:
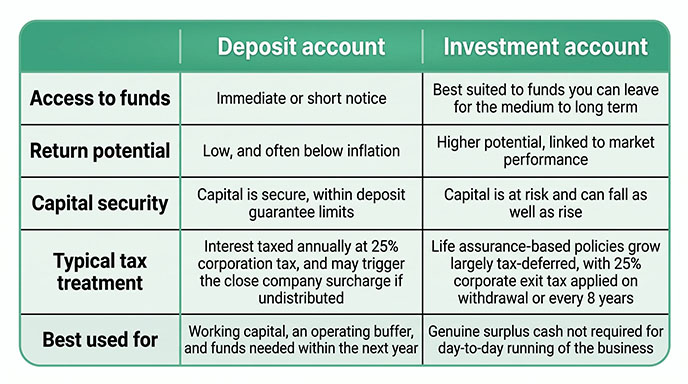
This is rarely an either-or decision. A business deposit account remains the right home for funds you might need at short notice, whether that is a working capital buffer, an upcoming tax bill or an unexpected cost. The trade-off is that deposit returns are typically modest, and once corporation tax and, where relevant, the close company surcharge are factored in, the real return after inflation can be marginal or negative.
An investment account is generally better suited to genuine surplus, money the business is confident it will not need for several years. It offers greater growth potential in exchange for capital risk and, in most cases, less immediate access. The table below sets out how the two compare.
For most businesses, a balanced approach is to keep three to six months of operating costs readily accessible on deposit, then look at investing any genuine surplus above that level. This keeps the company’s day-to-day resilience intact while putting longer-term cash to more productive use.
A close company, broadly one controlled by five or fewer participants, can face an additional tax charge known as the close company surcharge.
Under Section 440 of the Taxes Consolidation Act 1997, a 20% surcharge applies to undistributed investment and estate income that is not paid out as a dividend within 18 months of the end of the accounting period in which it arose. There is no surcharge where the relevant excess is €2,000 or less, with marginal relief where it is only slightly above that threshold, but for businesses retaining meaningful surplus, the surcharge can add materially to the overall tax burden of holding cash on deposit.
Investing through certain structures can help to manage this exposure.
For example, life assurance-based investment policies, sometimes called corporate investment bonds, are not subject to the close company surcharge. Growth within the policy accumulates largely free of annual tax, with corporate exit tax, currently 25%, only applying when the company withdraws funds, encashes the policy or reaches the eight-year deemed disposal point.
This deferred tax treatment allows returns to compound over time, rather than being reduced each year by tax and the ongoing threat of a surcharge, as can happen with interest sitting undistributed in a deposit account.
Before committing company funds, it is worth thinking through a few key areas.
Risk tolerance and investment horizon should shape the strategy, since money earmarked for a near-term goal calls for a more cautious approach than funds set aside for five years or more.
Regulatory compliance also matters: any advice or investment should come through a suitably qualified financial adviser, and larger decisions should be properly documented and approved by the board to reflect directors’ duties to the company.
It is also worth considering how a corporate investment strategy fits with the business’s wider plans, including any future sale, restructuring or transfer of ownership. For business owners thinking further ahead, our guide to succession planning for Irish business owners looks at how business assets, including corporate investments, can be structured with succession in mind.
Finally, no investment strategy should be left untouched. Markets move and business needs change, so a corporate investment account should be reviewed regularly to make sure it still reflects the company’s goals.
A corporate investment account can be a genuinely effective way to make better use of surplus business funds, but getting the structure right matters. The right choice depends on the company’s cash flow needs, risk appetite, tax position and future plans, and getting any of these wrong can be costly to unwind later. This is where professional advice earns its place.
At Fairstone, our wealth management and investment planning services help business owners to build a corporate investment strategy tailored to their company’s financial position, risk appetite and long-term plans. If you are considering opening a corporate investment account, book a no-obligation consultation with Fairstone to explore how your business’s surplus cash could work harder for you.
Sources
Revenue Commissioners, Life Assurance Exit Tax
Revenue Commissioners, Basis of Charge to Corporation Tax (trading vs non-trading income rates)
Disclaimer
This article is for general information purposes and is not an invitation to deal or address your specific requirements. Any expressions of opinions are subject to change without notice. The information disclosed should not be relied upon in their entirety and shall not be deemed to be, or constitute, advice. Although endeavours have been made to provide accurate and timely information of the various source material, there can be no guarantee that such information is accurate as of the date it is received or that it will continue to be accurate in the future.
