If you already contribute to a pension through your employer but want to build a larger retirement fund, an AVC pension could be one of the most powerful tools available to you. Additional voluntary contributions sit on top of your existing workplace pension, carry the same generous tax relief and give you greater control over your retirement income. This guide covers everything you need to know about AVCs in Ireland, from the basics through to AVC limits, PRSA AVCs and how to time your contributions for maximum effect.
An AVC pension, or Additional Voluntary Contribution pension, is a voluntary top-up to your existing occupational pension scheme. Rather than replacing your existing contributions, AVCs add to them, helping you build a larger retirement pot on your own terms.
In practical terms: if your employer requires you to contribute 5% of your salary to a pension scheme and your age-related limit allows 25%, you could make AVC contributions of up to the remaining 20% and receive full income tax relief on every euro. The fund grows tax-free and a portion can be taken as a tax-free lump sum when you retire.
For PAYE workers in Ireland, AVCs are one of the most effective ways to reduce your income tax bill while building long-term retirement wealth. The relief is immediate, the growth is tax-free, and the benefit compounds over time. For a deeper overview of how all pension contributions work in Ireland, see our guide to pension contributions in Ireland.
Anyone who is a member of an occupational pension scheme in Ireland can typically make AVC contributions, provided the scheme rules permit it. This covers both public and private sector employees. AVCs are particularly common among teachers, nurses, civil servants, and HSE workers who want to supplement their occupational pension, but they are equally relevant for any private sector employee with unused contribution capacity.
If your employer does not offer AVCs within the existing scheme, they are legally required to provide access to a PRSA AVC as an alternative. This ensures that all employees in pensionable employment have a route to make additional voluntary contributions, regardless of scheme structure.
AVC tax relief in Ireland is granted at your marginal (highest) rate of income tax, in the same way as relief on standard pension contributions:
For salary-deducted AVCs through payroll, relief is applied automatically at source. For once-off or PRSA AVC contributions made outside of payroll, you claim relief directly through Revenue myAccount (PAYE workers) or ROS (self-employed individuals).
Beyond the upfront tax saving, AVC contributions also benefit from tax-free growth inside the fund. Unlike investments held outside a pension, there is no capital gains tax, DIRT or deemed disposal exit tax applied to returns within an AVC fund. This makes AVCs one of the most efficient long-term savings structures available in Ireland, particularly for higher-rate taxpayers.
AVC limits in Ireland are set by Revenue and follow the same age-related percentage structure as all pension contributions. Your total pension contributions, meaning your standard employee contributions and any AVCs combined, cannot exceed the relevant percentage of your gross earnings, subject to an earnings cap of €115,000.

Source: Revenue.ie
Employer contributions do not count against these limits, so the full percentage applies to your personal contributions. You can contribute more than the threshold, but tax relief only applies up to the limit. Unused capacity in any given year cannot be carried forward, so reviewing your position before 31 October each year is worthwhile.
Example: A 50-year-old earning €120,000 whose employer deducts 5% of salary as standard pension contributions is already using €6,000 of their €34,500 allowance (30% of €115,000). They could make AVCs of up to €28,500 (23% of actual salary) and receive full income tax relief on the entire amount.
A PRSA AVC (Personal Retirement Savings Account AVC) is an individually arranged product that allows members of an occupational pension scheme to make additional voluntary contributions outside of their employer’s scheme. Where a standard AVC is typically managed through the employer’s pension provider, a PRSA AVC is set up directly with a provider of your choice.
This offers a number of practical advantages: greater investment choice, full portability if you change employer and the flexibility to start, pause, or increase contributions at any time without penalty. From 1 January 2025, employer contributions to a PRSA are capped at 100% of the employee’s salary; contributions above this limit are treated as a benefit in kind under Revenue rules.
The same age-related limits on AVC tax relief apply to PRSA AVCs as to all other contributions. For a full breakdown of how PRSAs work and how they compare to occupational pension structures, see our guide to what is a PRSA in Ireland.
Making AVCs through your occupational scheme involves a few straightforward steps:
One important deadline to keep in mind: AVC contributions for the previous tax year must be made before 31 October of the following year. For those using Revenue Online Service (ROS), the deadline is 18 November. This means a contribution made before 31 October 2026 can be backdated to the 2025 tax year, allowing you to reduce last year’s income tax bill even in the current year.
One of the most strategic uses of AVCs in Ireland is to boost the tax-free lump sum you can access at retirement. Revenue rules on lump sums differ slightly depending on your pension type:
Many employees in the final years before retirement make targeted lump sum AVC contributions specifically to maximise this tax-free amount. Timing these correctly, particularly in relation to the October deadline and your years of scheme membership, can make a very significant difference to the net amount you receive. This is one of the most financially impactful decisions available in the run-up to retirement and one where expert guidance is worth seeking.
At retirement, your AVC fund can be used in several ways, either individually or in combination:
Choosing the right combination depends on your overall pension position, other income sources in retirement, tax situation, and personal priorities. If you are also contributing to a defined contribution pension through your employer, how your AVC interacts with that scheme at drawdown is something your advisor should model in advance.
Earlier contributions benefit most from compound growth, but it is never too late to start making additional voluntary contributions. The age-related limits increase as you get older, which means those in their 50s and 60s can put the most away with full tax relief at a time when they are often earning more than at any other point in their careers.
Three situations where AVCs in Ireland are particularly valuable:
For more context on how contribution timing affects long-term outcomes, see our guide on why starting a pension in your 30s can add 40-60% more wealth. And if early retirement is on your radar, our guide to planning for early retirement in Ireland explains how AVCs fit into an accelerated retirement strategy.
AVCs are one of the most effective and underused financial tools available to employees in Ireland. Whether you want to reduce your tax bill before year end, catch up on missed retirement savings, or build toward a specific lump sum at retirement, the right AVC strategy depends heavily on your individual circumstances: your age, income, existing pension arrangements, scheme rules and retirement timeline.
Getting the amount, structure, and timing right requires more than a rough calculation. At Fairstone, our pension advisors work with employees, business owners and public sector workers across Ireland to design AVC strategies that make the most of what Revenue allows. We will assess your current position, identify any unused allowance and map out the most tax-efficient route to your retirement goals.
Explore our Retirement Planning service to find out how we can help or get in touch for a no-obligation conversation with one of our advisors.
Updated 19th June 2026
Source:
Related articles:
Pension Contributions in Ireland: What You Need to Know
Is Pension Consolidation Right For You?
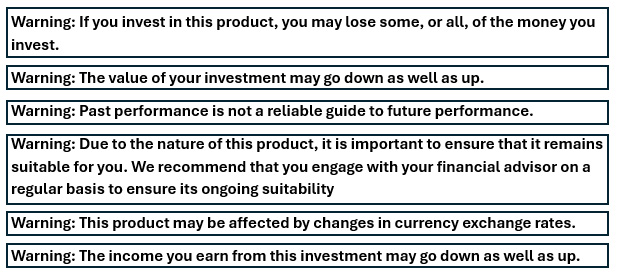
The tax treatment is dependent on individual circumstances and may be subject to change in future. This article is for general information purposes and is not an invitation to deal or address your specific requirements. Any expressions of opinions are subject to change without notice. The information disclosed should not be relied upon in their entirety and shall not be deemed to be, or constitute, advice. Although endeavours have been made to provide accurate and timely information of the various source material, there can be no guarantee that such information is accurate as of the date it is received or that it will continue to be accurate in the future.
